



 For all latest news, follow the Daily Sun's Google News channel.


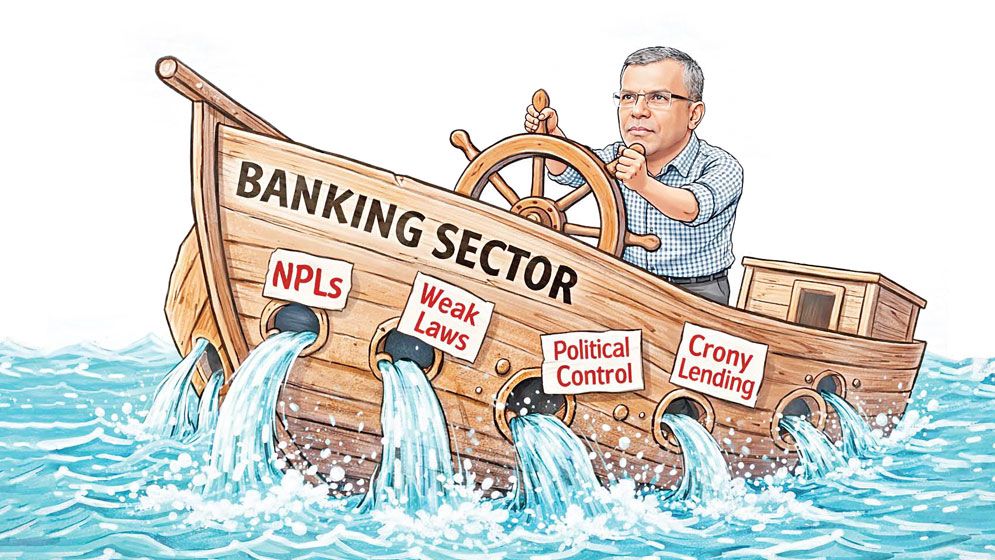
The new Bangladesh Bank governor has assumed office amid a deepening crisis in the banking sector, marked by record levels of non-performing loans (NPLs), capital shortfalls and a steady erosion of depositor
confidence.
Economists and senior bankers warn that piecemeal administrative measures will not be enough and that that the situation now demands far-reaching legal reforms, stronger governance frameworks and greater autonomy for the central bank.
As of September 2025, total NPLs across the banking system had climbed to Tk6.44 lakh crore,
accounting for nearly 36% of all outstanding loans – more than double the roughly 17% recorded a year earlier. In several banks, the proportion of bad loans has surged to between 60% and 70%, leaving institutions effectively paralysed.
Against this backdrop, five struggling Shariah-based lenders – First Security Islami Bank, Social Islami Bank, Union Bank, Global Islami Bank and EXIM Bank – have been merged to form Sammilito Islami Bank PLC. Together, they hold deposits of Tk1.31 lakh crore and serve more than 7.5 million customers.
Delivering a successful merger and restoring public trust will be a major early test for the new governor under the new government.
At the same time, the process of cancelling the licences of nine non-bank financial institutions is continuing.
Only two banking laws enacted
So far, the interim government has enacted just two banking-related ordinances: the Bank Resolution Ordinance and the Deposit Insurance Ordinance. Other key reform initiatives remain stalled.
Officials at Bangladesh Bank say proposed amendments to the Bangladesh Bank Order, 1972, and the Bank Company Act have been held up at the finance ministry.
According to central bank officials, a revised draft amendment to the Bangladesh Bank Order – intended to strengthen the regulator’s autonomy – has been awaiting approval for more than four months.
The original proposal sought to remove bureaucrats from the Bangladesh Bank board, where three government officials currently sit.
Following objections from the finance ministry, the proposal was revised to allow one bureaucrat instead of three. It also recommends granting the governor the rank of a minister and requiring the governor to take the oath of office before the chief justice.
Despite these concessions, the amendment has yet to receive clearance.
Proposed Bank Company Act amendments
A second major reform package concerns amendments to the Bank Company Act. Approved by the Bangladesh Bank board in October last year and submitted to the finance ministry, the draft contains 45 proposed changes.
Among the key provisions are plans to reduce the maximum size of bank boards from 20 directors to 15, and to require independent directors to make up at least half of the board, compared with the current minimum of three.
It also proposes that independent directors be selected from a vetted pool shortlisted by an expert committee.
Another significant proposal would curb ownership concentration by preventing any individual, family or institution from holding more than a 5% stake in multiple banks.
Bangladesh Bank says the reforms are designed to improve governance and strengthen oversight across both private and state-owned banks.
However, private sector resistance has been strong. The Bangladesh Association of Banks has formally objected to the finance ministry, particularly over the proposed ownership cap.
Recommended Stories
Experts question delay
The wider economic backdrop remains challenging. Inflation has stayed above 8%, while lending rates of 14%-15% – with the policy rate at 10% – have dampened private investment. Liquidity pressures at several banks have also fuelled depositor anxiety.
Dr Zahid Hussain, former lead economist at the World Bank’s Dhaka office, said the prolonged delay was hard to justify.
“This is not a new file,” he said, noting that the draft laws were prepared following extensive consultations involving the finance ministry, Bangladesh Bank and other stakeholders.
He added that the proposed reforms were reflected in International Monetary Fund mission reports and incorporated into the government’s Letter of Economic and Financial Policies, signed by both the finance minister and the Bangladesh Bank governor.
“After that process, the role of the finance ministry is straightforward – review the draft, clear it, or clearly explain why it cannot be cleared,” he told the Daily Sun. Leaving the file idle for months raises concerns, he said.
Dr Zahid suggested the delay was driven more by questions of authority than by technical disagreements.
“One key element of the reform is reducing the representation of the finance ministry on the Bangladesh Bank board. From that perspective, the issue is control,” he said.
He added that central bank independence should not be interpreted narrowly. “It is not only about fiscal dominance. It also involves bureaucratic dominance and influence from business lobbies.”
Dr Mustafa K Mujeri, a distinguished economist and former chief economist of Bangladesh Bank, stressed that the new government must move quickly to finalise legal reforms, reinforce regulatory independence, ensure transparency, publish forensic audit findings and hold financial offenders to account.
“Without decisive steps,” he warned, “structural weaknesses in the banking sector could continue to undermine financial stability and broader economic recovery.”