


 For all latest news, follow the Daily Sun's Google News channel.


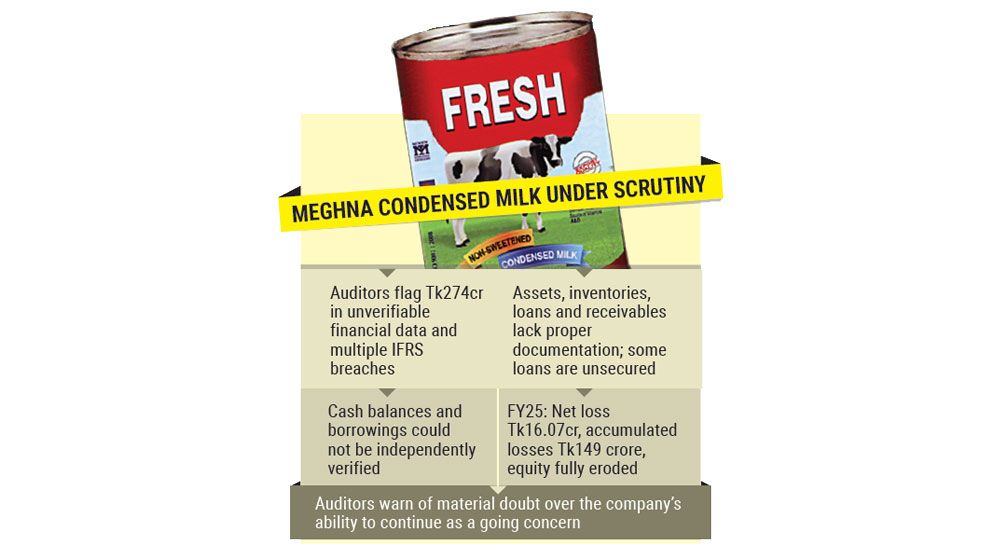
Serious concerns have emerged over the financial transparency and governance of Meghna Condensed Milk Industries Limited, a listed company, after auditors said financial information amounting to around Tk274 crore could not be verified due to the company’s failure to provide sufficient and appropriate audit evidence.
In their audit opinion on the financial statements for the year ended 30 June 2025, the auditors flagged widespread weaknesses in accounting records, a lack of supporting documentation, denial of audit procedures, and multiple departures from International Financial Reporting Standards (IFRS).
Combined with mounting losses and negative equity, the auditors said these issues raise material uncertainty about the company’s ability to continue as a going concern.
The Z-category company currently does not have a company secretary, and no official statement was available from management regarding the audit findings.
Commenting on the matter, Debabrata Kumar Sarkar, former chief research officer of BRAC EPL Investment Limited, told the Daily Sun that the scale of unverifiable financial information, around Tk274 crore, is alarming for a listed company.
“Such extensive audit limitations seriously erode investor confidence and expose minority shareholders to significant risk,” he said.
“These weak companies are most susceptible to manipulation. The regulator should be more proactive in protecting investors, and companies facing serious audit allegations should be brought under disciplinary action.”
Questionable assets and records
Auditors reported that property, plant and equipment were stated at Tk111 crore, but the company failed to maintain proper accounting records to substantiate the balances.
The assets were revalued by Lam International Inspection Ltd, which is not approved by the Bangladesh Securities and Exchange Commission (BSEC) as a valuer, casting doubt on the reliability of the reported figures.
Inventories amounting to Tk3.01 crore were also reported without inventory ledgers or stock movement records. Management provided only a certificate stating the closing stock balance, which auditors deemed insufficient for verification.
Advances, deposits and prepayments totaling Tk5.58 crore, carried forward from previous years, could not be assessed for recoverability.
Management failed to confirm whether future economic benefits would arise from these balances, prompting auditors to warn that any non-recoverable amounts should be written off to avoid asset and profit misstatements.
Trade receivables and other receivables of Tk90 lakh raised further concern. No supporting documents were provided, and the balances had remained unadjusted for more than one year.
In line with IFRS-9, auditors advised provisioning for expected credit losses.
The situation was compounded when management denied permission to send balance confirmation requests and failed to provide debtor addresses, significantly restricting audit scope.
Loan transparency under question
An unsecured loan of Tk3 crore was recorded without any ledger, loan agreement or evidence of purpose.
As the transaction appeared to involve related parties, auditors noted that it should have been conducted through banking channels. However, incomplete bank statements prevented verification of loan receipts and repayments.
Cash and cash equivalents were shown at Tk49 lakh, but bank confirmations were not received by the reporting date. Cash in hand was supported only by management certification, without independent verification.
Long-term borrowings of Tk64.27 crore from Sonali Bank Limited were recorded without loan statements or contractual documentation.
The company also failed to separately classify current and non-current portions of the loans, a clear violation of IAS-1. As a result, auditors said the accuracy of loan balances and finance costs could not be confirmed.
Short-term borrowings through cash credit and overdraft facilities totaled Tk40.38 crore. Of this, Tk22.77 crore borrowed from Sonali Bank lacked supporting loan statements, while only the balance with First Security Islami Bank Limited was confirmed. Liabilities for expenses and other financial obligations amounting to Tk45.19 crore, carried forward from previous years, also lacked sufficient documentation, preventing auditors from verifying their completeness and accuracy.
Mounting losses, going concern doubts
Beyond documentation failures, the company’s financial performance reflects deep distress.
Meghna Condensed Milk Industries Limited posted a net loss of Tk16.07 crore during the year, pushing accumulated losses to Tk149 crore and fully eroding shareholder equity.
As of 30 June 2025, the company reported a negative net asset value per share of Tk16, earnings per share of negative Tk10.05, and net operating cash flow per share of negative Tk0.49.
Auditors concluded that these conditions, together with unresolved financial irregularities, constitute a material uncertainty that may cast significant doubt on the company’s ability to continue as a going concern.
Meghna Condensed Milk Industries Limited, a subsidiary of Meghna Group of Industries KA Limited, produces both sweetened and unsweetened condensed milk.
Read More