


 For all latest news, follow the Daily Sun's Google News channel.


Merged Five Banks
Customers suffer as stringent rules complicate deposit withdrawals
Despite limited fund releases after the merger, many customers remain unable to access savings and fixed deposits due to rigid eligibility criteria and phased payouts
Mousumi Islam, Dhaka
Published: 06 Jan 2026, 12:00 AM
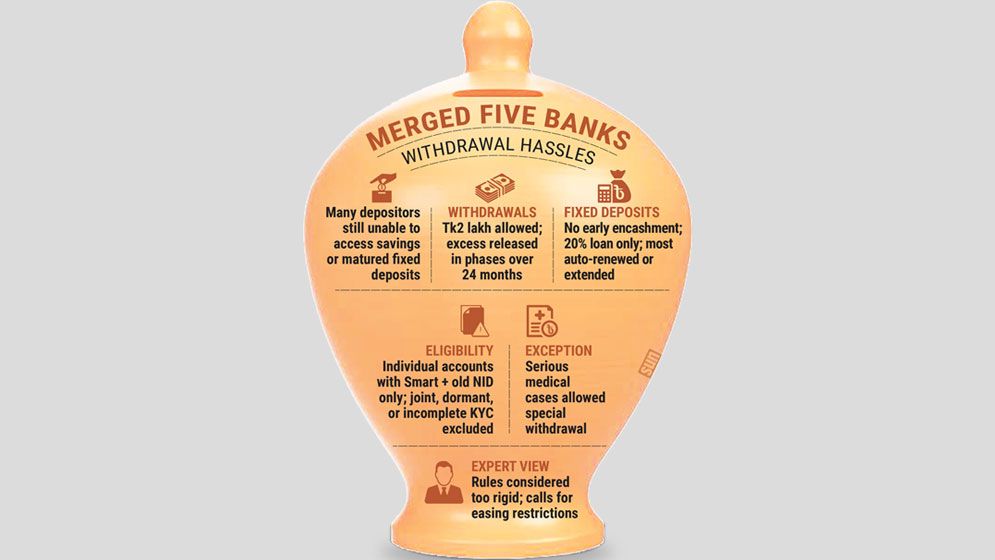
Many depositors of the newly formed Sammilito Islami Bank continue to face restrictions on withdrawing their own money, despite assurances that deposits are gradually being released following the merger of five troubled Islamic banks.
Nesar Uddin, who had placed a fixed deposit of Tk15 lakh with Union Bank, said his deposit matured on 15 December, but he was unable to withdraw the funds when he visited the bank on Sunday.
“As of 22 December, the total amount of my deposit, including profit, stands at around Tk28 lakh. Although this amount has been credited to my savings account, I cannot withdraw any money,” he told the Daily Sun. “I was told that fixed deposits that matured after 4 November cannot be withdrawn immediately.”
Arman Rahman, a customer of Exim Bank, described a different experience. He said he has Tk5 lakh in his savings account and an active DPS account.
“According to Bangladesh Bank regulations, I wanted to withdraw Tk2 lakh from my savings account, but the bank did not give me any money,” he said. “They told me that even though I have funds in my savings account, I cannot withdraw anything because I have a DPS account.”
Sayem Hossain, a customer of First Security Islami Bank, said his withdrawal request was rejected because he does not have a smart national identity (NID) card.
“I was not given any money because I do not have a smart NID card. I don’t fully understand what this means,” he said. “I opened my account exactly as the bank instructed at the time. I don’t understand why this issue is being raised now.”
Although Sammilito Islami Bank -- formed through the merger of First Security Islami Bank, Social Islami Bank, Union Bank, Global Islami Bank and Exim Bank -- has begun releasing deposits to customers, many depositors remain unable to access their funds due to a range of conditions.
Bangladesh Bank has already approved the final policy governing the formation of Sammilito Islami Bank. All branches of the five merged banks are now operating under the new name, with updated logos and signboards installed nationwide.
Commenting on the situation, veteran banker and former Chairman of Global Islami Bank Md Nurul Amin said depositor anxiety has eased somewhat following the limited release of funds, but significant problems remain.
“It is unfortunate that many customers are unable to withdraw their money due to various conditions -- whether small or large, reasonable or unreasonable,” he said.
“It is completely unreasonable to say that a customer cannot withdraw money from a savings account simply because they have a DPS account. Moreover, if a bank can identify a customer, deposits should be returned even without a smart NID.”
He urged the authorities to relax withdrawal conditions to ease depositor suffering.
Strict withdrawal rules
Under Bangladesh Bank guidelines, depositors of the five banks with up to Tk2 lakh in their current or savings accounts have been allowed to withdraw funds from January 1. For balances exceeding Tk2 lakh, withdrawals will be permitted in phases over a maximum period of 24 months.
For general depositors, the next Tk1 lakh may be withdrawn three months after the scheme becomes effective, followed by additional withdrawals of Tk1 lakh at six, nine, 12, 15, 18 and 21 months.
The remaining balance will be payable after 24 months. The same schedule applies to institutional depositors.
Special rules also apply to term and fixed deposits.
Depositors will not be allowed to withdraw funds before maturity, and even after maturity, withdrawals will not be permitted freely. Instead, depositors may avail investment or loan facilities of up to 20% against their fixed deposits.
Three-month fixed deposits will be automatically renewed three times after the scheme takes effect, while deposits with tenures of three to six months will be renewed twice. Deposits of six to 12 months will also be renewed twice.
Fixed deposits of one to two years will be converted into three-year deposits; two to three years into four-year deposits; and three to four years into five-year deposits. Deposits exceeding four years will be payable upon maturity.
However, humanitarian exceptions have been included for depositors suffering from serious illnesses such as cancer or those undergoing kidney dialysis, allowing withdrawals beyond the stipulated limits for medical needs.
Tight eligibility criteria
According to the policy, only individual depositors with current or savings accounts -- and without any MTDR (Mudaraba Term Deposit Receipt) or scheme accounts -- are currently eligible to withdraw funds.
At present, only depositors who possess both a verified smart NID card and an old NID are allowed to make withdrawals.
Dormant accounts, accounts lacking required KYC documents, joint accounts, and accounts opened using passports or birth registration certificates are excluded for now. Decisions regarding these accounts will be announced later.
If a depositor holds multiple current or savings accounts, balances across all such accounts will be consolidated, and liabilities adjusted before determining withdrawal eligibility.4 November 2025 has been set as the reference date for calculating withdrawal limits, as the five banks were declared non-functional on 5 November.
If an account balance increased after 4 November, the balance as of that date will be used to determine withdrawal eligibility. If the balance decreased by 24 December, 2025 -- the date Sammilito Islami Bank began operations -- the lower balance will be considered.
For example, if a depositor had Tk1.45 lakh on 4 November and the balance later fell to Tk1.20 lakh, the depositor will be able to withdraw the current balance.
If a depositor had Tk5 lakh on 4 November and later withdrew Tk50,000, leaving Tk4.5 lakh, they will be eligible to withdraw Tk1.50 lakh.
However, if the balance fell to Tk2 lakh after withdrawals, no further withdrawal will be permitted.
Read More