


 For all latest news, follow the Daily Sun's Google News channel.


LNG dependence trap in power and energy sector: Debt, subsidies and a silent economic strain?
Zulkarnain Saer
Published: 27 Feb 2026, 04:21 PM
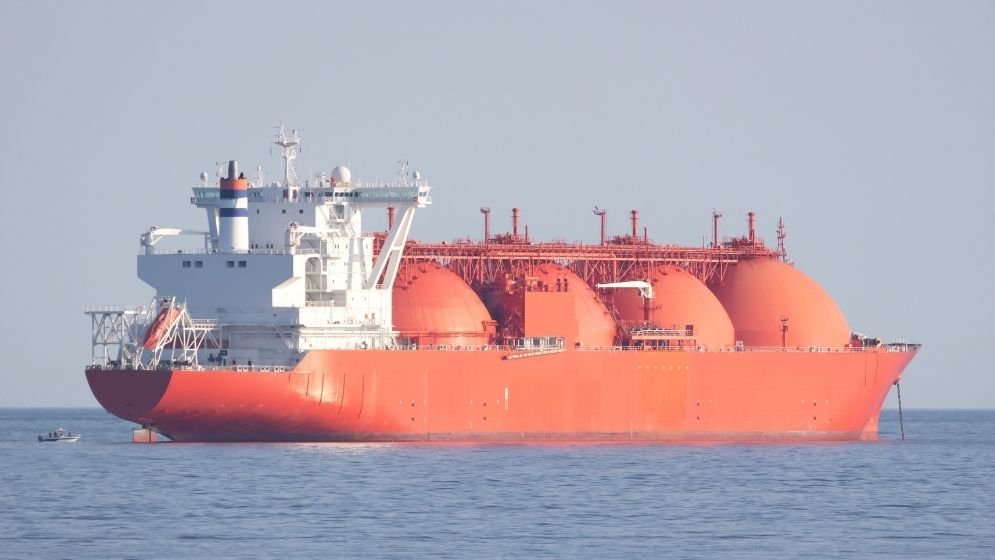
one owned by US company Excelerate Energy and the other by Summit Group-
Bangladesh’s power and energy sector is now facing a serious challenge. Years of inadequate investment in domestic oil and gas exploration have led to declining production. To bridge the gap, the country began importing liquefied natural gas (LNG) in 2018 under long-term agreements with Qatar and Oman. From 2019, imports from Singapore’s spot market and the United States also increased. What initially appeared to be an emergency solution has, within a few years, turned into a costly dependence.
Although the BNP pledged in its 31-point
reform outline and election manifesto to prioritise domestic gas exploration
and renewable energy, some deviation is now visible after assuming office. The
Energy Ministry recently announced a 100-day action plan. It shows that, much
like the Awami League before it, the BNP is also planning to expand LNG import
capacity. State Minister for Energy Iqbal Hassan Mahmood has said additional
LNG terminals will be constructed in Cox’s Bazar. This raises a pressing
question: is the sector being locked into an expensive cycle of import
dependence?
The high cost of LNG imports
At present, the country’s daily gas supply
capacity stands at around 3,000 million cubic feet, of which LNG accounts for
1,100 million cubic feet. This gas is supplied through two terminals – one
owned by US company Excelerate Energy and the other by Summit Group.
Although the imported portion appears small
in volume, the economic burden is immense. In 2022, pressure from energy
imports contributed significantly to a sharp decline in Bangladesh Bank’s
foreign exchange reserves. The Awami League government had initially pursued
LNG imports as part of a broader ambition to match regional industrial
competitors such as Japan and South Korea. However, the resulting import dependence
later intensified financial stress and public dissatisfaction. The energy
sector became one of the most criticised areas of governance.
Despite these lessons, a new energy master
plan was approved at a time when reserves were already strained, envisioning
LNG imports worth up to $3 billion per month.
According to Petrobangla, the country imports
an average of 115 LNG cargoes annually, each costing up to Tk500 crore. From
FY2018-19 to FY2024-25, total LNG import expenditure reached approximately Tk205,254
crore, with subsidies exceeding Tk36,765 crore during the same period.
Petrobangla exhausted around Tk28,000 crore
from its own funds and drew heavily from the Gas Development Fund – which
consists entirely of public money intended for domestic gas exploration. Even
so, it was unable to meet import bills and had to borrow about Tk4,500 crore
from the World Bank in the current fiscal year.
Official figures indicate that, compared to
2009, power generation costs have risen by 330%, gas prices by more than 400%
due to LNG imports, and financial losses in the power sector by 1,300%.
18 times costlier than domestic gas
Despite repeated gas price hikes since LNG
imports began in 2018, the production cost of domestic gas remains around Tk3
per cubic metre, up from Tk1 previously. By contrast, imported LNG costs nearly
Tk55 per cubic metre – roughly 18 times higher. Selling this expensive gas at
lower regulated prices has widened subsidy requirements. Moreover, LNG-based
power plants have higher generation costs, pushing up the average cost of
electricity.
LNG contracts are dollar-denominated,
exacerbating foreign currency shortages. As reserves decline and the taka
depreciates, import costs rise further, creating a vicious macroeconomic cycle.
Mounting pressure on Petrobangla and PDB
Before LNG imports began in 2018, Petrobangla
had fixed deposits worth Tk28,000 crore derived from dividends of its 13
subsidiary companies. Within four years, these funds were depleted. Once known
as a profitable entity, Petrobangla is now increasingly dependent on loans,
bank borrowing and government guarantees.
Meanwhile, arrears of the Bangladesh Power Development Board (PDB) have reached between Tk40,000 crore and Tk50,000 crore, driven by capacity payments and high production costs.
Investment imbalance
Over the past seven years, about Tk2.05
trillion has been spent on LNG imports, while investment in domestic gas
exploration and drilling has remained minimal. In FY2025-26, the projected cost
of importing 115 LNG cargoes is around Tk58,000 crore. In contrast, the Annual
Development Programme allocation for local gas exploration surveys and well drilling
stands at Tk1,129 crore – meaning LNG import expenditure this fiscal year is 51
times higher than the allocation for domestic exploration.
Each year, more than Tk20,000 crore is
allocated to the power sector, while less than Tk1,500 crore goes to the energy
sector. Yet without fuel, electricity generation is impossible.
Despite significant potential for solar, wind
and other renewable sources, only 3% of electricity currently comes from
renewables. While fossil fuel-based projects receive substantial incentives,
renewable initiatives do not enjoy similar policy support.
Subsidy burden on the budget
In FY2024-25, subsidies in the gas and LNG
sector amount to nearly Tk8,900 crore, up from around Tk6,000 crore the
previous year. These subsidies come from the national budget, constraining
spending on education, healthcare, social protection and critical
infrastructure.
Despite high LNG import spending, gas supply
has not improved. In FY2024-25, daily gas supply averaged 2,526 million cubic
feet, lower than the previous year. In February this year, Petrobangla supplied
an average of 2,200 million cubic feet per day. In other words, LNG imports are
rising, yet energy security remains unstable.
What are the alternatives?
First, accelerate the transition to renewable
energy. Bangladesh has vast potential for rooftop solar systems, which should
be fully utilised. Solar and wind projects in industrial zones must be
expanded.
Second, strengthen domestic gas exploration.
Both onshore and offshore blocks require greater international and local
investment. An accelerated well-drilling programme and a substantial increase
in the exploration budget are essential.
Even the discovery of a medium-sized gas field could reduce import expenditure by thousands of crore taka annually.
The opinion was originally published on Bangla Outlook.