


 For all latest news, follow the Daily Sun's Google News channel.


ADB trims growth forecast to 4% for FY27
Inflation projected to rise to 9% as energy shortages, domestic constraints weigh on recovery
Daily Sun Report, Dhaka
Published: 24 Sep 2026, 12:00 AM
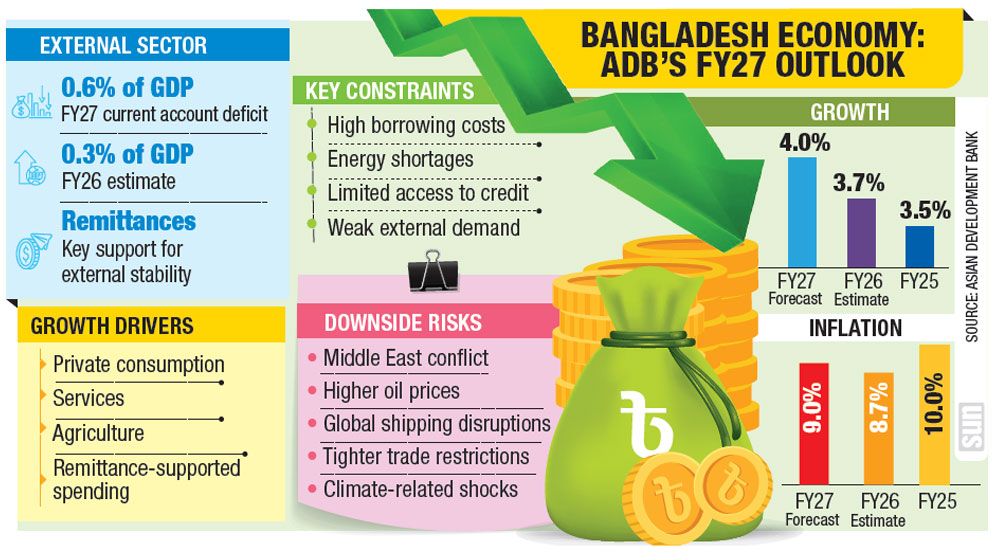
The Asian Development Bank (ADB) has lowered its forecast for Bangladesh’s economic growth in the fiscal 2026-27 to 4%, down from 4.5% projected in July and 4.7% in April.
In its latest Asian Development Outlook (ADO), released on Wednesday, the Manila-based lender said Bangladesh’s economy is expected to grow by 3.7% in FY26, up from 3.5% in FY25.
The latest forecast points to a moderate recovery, supported by stronger consumption and investment as political uncertainty eases following the general election earlier this year.
However, economic activity slowed in the final quarter of FY26 amid supply chain disruptions linked to the conflict in the Middle East, although ADB expects the overall impact to remain limited.
“Bangladesh’s economy is beginning to recover, but the recovery remains vulnerable to external shocks and domestic constraints,” said ADB Country Director for Bangladesh Qingfeng Zhang.
He said reforms in macroeconomic management, the financial sector, energy security and the business environment would be important to unlock private investment, create quality jobs and support more resilient growth.
Inflation is expected to remain a major challenge. ADB estimates that inflation eased to 8.7% in FY26 from 10.0% in FY25, but forecasts it to rise to 9.0% in FY27.
The lender attributed persistently high inflation to energy shortages, elevated production and transport costs, possible shipping disruptions, the delayed effects of El Niño on food prices and gradually easing monetary conditions.
The current account deficit is projected to widen to 0.6% of GDP in FY27 from an estimated 0.3% in FY26 as imports grow faster than exports.
ADB expects remittance inflows to remain resilient despite continued tensions in the Middle East.
Strong remittances and higher foreign exchange reserves are expected to support external stability, although this will depend on adequate financial inflows, exchange rate flexibility and prudent macroeconomic management.
Services and agriculture are expected to support growth in FY27, while industry and investment may remain constrained by high borrowing costs, limited access to credit, energy shortages and weak external demand.
Private consumption, supported by remittances, is expected to remain the main driver of growth. However, persistent inflation is likely to continue weighing on household purchasing power.
ADB warned that a prolonged Middle East conflict, higher oil prices, disruptions to global shipping, tighter trade restrictions and weaker growth in major export markets could further weigh on the economy.
Domestic risks include exchange rate pressures, banking-sector stress, delays in fiscal reforms and lower-than-expected development spending, while climate-related shocks could further weaken growth and keep inflation elevated.