


 For all latest news, follow the Daily Sun's Google News channel.


From capital to capability
Can Chinese investment help Bangladesh build skills, suppliers, globally competitive industries?

Three decades ago, nine in 10 people in Anwara’s Bairag union depended on farming and fishing on the Bay, says Nurul Alam, a resident of Guapanchak village. Then came the Korean EPZ, and slowly, jobs followed. Now comes another transformation.
Where paddy fields stood 18 months ago, about 800 acres have been cleared and access roads cut through what was once a patchwork of paddy fields.
Bangladesh’s most ambitious dedicated industrial zone for Chinese investment is beginning to take physical shape, and for people living around it, the change is no longer an announcement on paper — it is visible.
“Once jobs open up at the China EPZ, boys and girls from here will be able to work without leaving their own area,” says Navidul Islam, a young man from the same village who watched an earlier generation travel to Chattogram city or elsewhere for work that did not exist in their locality.
The zone formally broke ground on 27 July 2026, though its supporting infrastructure has an implementation period running to December 2031; BEZA expects 60% of the plots ready for construction within three years.
After years of delay, the question is no longer whether the Chinese Economic and Industrial Zone at Anwara will be built. It is how quickly land becomes factories, factories become supply chains, and supply chains become productive capacity.
More than 30 Chinese companies have reportedly committed around $500 million to the zone so far, according to the Chinese ambassador, with total investment eventually expected to exceed $1 billion.
BIDA Executive Member Nahian Rahman Rochi puts the zone’s full design target at around $1.3 billion, with the potential to create more than one lakh jobs.
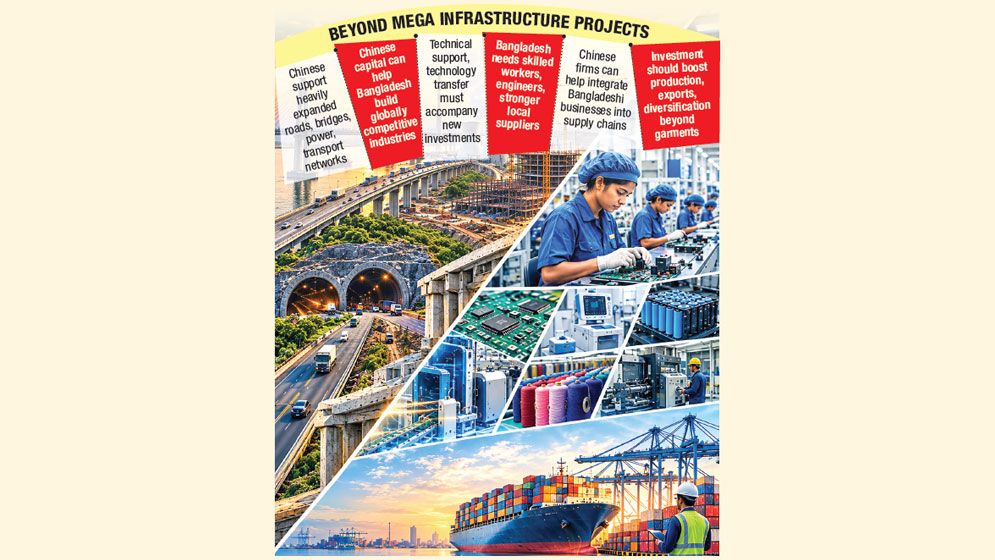
For years, the most visible imprint of China-Bangladesh ties was concrete and steel — roads, bridges, power plants, tunnels, railways.
That was the first phase. The emerging question is different: what can Chinese capital help Bangladesh produce? That shift is beginning to show beyond Anwara.
The pipeline is already turning industrial
Chinese companies accounted for nearly two-thirds of the new investment commitments secured by the Bangladesh Export Processing Zones Authority (BEPZA) in FY26: 23 Chinese-owned or joint-venture companies proposing $498.86 million out of $717.71 million secured from 36 companies.
The proposed projects span electronics, drones, medical devices, logistics, light engineering, textiles, footwear, leather goods and processed food — notably different from the garment-and-textile mix that has defined Chinese manufacturing here for two decades.
At BIDA, the pattern repeats: of more than $400 million from a $1.5 billion 2025 pipeline that has reached decision or implementation stage, nearly $367 million — about 92% — came from Chinese companies.
Then came the headline figure from Prime Minister Tarique Rahman’s June visit to China: 12 Chinese companies proposed $9.21 billion, spanning energy, infrastructure, logistics, manufacturing, environmental services and education.
The number is eye-catching. But it is not yet investment.
A relationship entering its second phase
Bangladesh and China marked fifty years of diplomatic relations last year. Over that half-century, economic cooperation expanded from trade into infrastructure financing, machinery and capital goods, with China becoming Bangladesh’s largest trading partner along the way.
The joint communiqué after the prime minister’s 22-26 June visit points toward something broader than another round of infrastructure deals.
The two countries committed to deepening cooperation in trade, e-commerce, and industrial and supply chains, with China pledging continued support for Bangladesh’s industrialisation and agricultural modernisation, and Bangladesh welcoming zero-tariff treatment across 100% of Chinese tariff lines. Both sides also agreed to advance the Mongla Port Facilities Modernisation and Expansion Project alongside Anwara.
The visit produced concrete follow-through too. Bangladesh and China signed 13 memoranda of understanding on 25 June, following talks between Tarique Rahman and Premier Li Qiang in Beijing.
China Road and Bridge Corporation was confirmed as Anwara’s formal developer, while separate agreements covered the proposed Teesta River project and the China-Myanmar Economic Corridor.
China’s Handa Group separately secured land in the Keraniganj Economic Zone for a planned $220 million investment.
Together, these amount to more than new infrastructure — an attempt to connect Chinese capital directly to Bangladesh’s factories, ports, economic zones and export industries, at a moment when Bangladesh has few alternatives left.
The country needs to diversify an export basket still dominated by garments, attract investment beyond its traditional base, create higher-productivity jobs, and prepare for a more competitive post-LDC environment.
Chinese capital could, in principle, touch every one of those goals — but only if it turns into production capacity, not simply a larger import bill with a different origin stamp.
Anwara: the test case
Nowhere will that be tested more directly. If the zone develops as planned, it need not be another industrial estate collecting factories that could have located anywhere — it could become a cluster, with Chinese manufacturers, Bangladeshi suppliers, logistics operators and service providers feeding each other’s demand.
That distinction is not a technicality: a single factory operating in isolation creates jobs and output; a functioning cluster multiplies those effects, generating demand for Bangladeshi packaging firms, engineering shops, transport operators and component manufacturers outside the zone’s fence, and creating a ladder for workers to move from assembly-line labour into technical and supervisory roles.
That ladder is exactly what Navidul Islam says is still missing next door.
Most young men in the area, he says, have found some connection to work at the neighbouring Korean EPZ, “but opportunities for locals in senior and skill-based positions are still comparatively limited. More opportunities need to be given to locals in these positions.”
His hope for the Chinese zone is specific: that skills training, not just headcount, determines who gets hired, and into what.
That concern is now finding its way into wider business policy discussions. The BCCCI has proposed setting up technical and polytechnic institutes to develop the skills needed to support greater Chinese investment and industrial expansion.
The proposal points to the gap between creating jobs and building the skilled workforce needed to move beyond basic assembly.
But none of that is automatic.
It depends on which companies move in, what they manufacture, and how deeply they root themselves in the surrounding economy rather than using Bangladesh as an assembly point between imported components and an export container.
Economists say a cluster is more than factories sharing a location — it emerges when firms build links through local suppliers, shared services, skilled labour and technology transfer. Anwara is still an emerging zone, not yet a mature cluster; its success will depend on whether such linkages develop.
The $9.21 billion question
The scale of what was proposed is hard to ignore, item by item: $4.5 billion from Sichuan Road & Bridge Group for the Dhaka-Chattogram Highway PPP; $1.65 billion from Zhongxin Environmental Protection Group for e-waste recycling; $890 million from Shanghai SUS Environment for waste-to-energy plants; $650 million from China Civil Engineering Construction Corporation for the Mongla Port Economic Zone.
Further proposals cover gas exploration, smart-meter manufacturing, cold-chain logistics, recycled textiles, lithium batteries, solar power, rolling-stock assembly, education and medicinal-herb cultivation.
The diversity matters as much as the total, suggesting Chinese interest reaching beyond garments and conventional infrastructure — if the proposals survive contact with reality.
BIDA officials have been candid: the figures came from the companies themselves and have not undergone verification. A proposal becomes meaningful only once it moves through a long chain — feasibility, approval, financing, land allocation, construction, production, exports and employment — and Bangladesh has watched previous investment announcements stall out well before that chain’s end.
Bangladesh has been here before, at larger scale.
When Xi Jinping visited Dhaka in 2016, China announced a roughly $20 billion package of infrastructure and energy commitments, alongside separate Belt and Road financing and joint-venture proposals. A decade on, only about half that pipeline has actually been financed.
“Signing an MoU does not mean every project will eventually be implemented,” CPD distinguished fellow Mustafizur Rahman said, noting several 2016 coal-fired power projects were later cancelled once Beijing shifted its financing priorities, while others stalled for years. The Anwara zone itself was one of the casualties he named, losing years to disputes over land acquisition and investment terms.
That caution is not merely historical: Bangladesh Power Development Board officials confirm 31 renewable energy projects — most Chinese-backed, worth a combined $5 billion — were cancelled after the interim government took office in 2024, a reminder that even recent Chinese commitments can unwind quickly when politics shift.
This push should be measured not by the size of announcements but by the number of projects that reach production.
The capability test
Even if every proposed dollar materialises, a second question follows: what does Bangladesh actually keep once the ribbon is cut?
A factory that imports nearly everything and exports finished goods still creates jobs and foreign exchange — that much is real. But one that trains Bangladeshi engineers, sources components locally and transfers know-how leaves behind something harder to build from scratch: capability. It is, in effect, the distinction Navidul Islam was making without the word for it.
That distinction should sit at the centre of Bangladesh’s China strategy: not simply how much will you invest, but how much will you produce here; not how many jobs, but how many involve technical training; how much will be sourced locally; what technology transfers; whether Bangladeshi firms enter the supply chain at all.
These questions matter most in the sectors BIDA has flagged as priorities — electronics, semiconductors, medical devices, EV batteries, advanced textiles, IT-enabled services — precisely where the gap between assembly and capability is widest.
The China-plus-one test
Chinese manufacturers are actively diversifying beyond China’s borders, and Bangladesh is one of several Asian destinations competing for that capital.
Vietnam has already shown what successful integration into that shift looks like, pairing foreign investment with export-oriented manufacturing at a scale Bangladesh has yet to match outside garments.
That gap is stark in raw numbers. As of September 2024, Chinese FDI stock in Bangladesh stood at just $1.41 billion — against $30 billion in Vietnam, $24 billion in Indonesia, $22 billion in Myanmar, $19 billion in Cambodia and $12.66 billion in Thailand.
Ke Changliang, chief adviser of the Chinese Enterprise Association in Bangladesh, put it bluntly, “The business environment in Bangladesh is still not as good as Vietnam or Indonesia. That’s the main reason.”
Chinese officials elsewhere point to a starker gap: economic-zone approvals taking about seven working days in China can take close to two years in Bangladesh.
Bangladesh brings real advantages — a large workforce, a sizeable domestic market, proximity to major Asian markets, decades of apparel manufacturing — but also weaknesses investors name consistently: infrastructure bottlenecks, land availability, customs delays, energy reliability, skills shortages.
Chinese capital cannot paper over these; a wave of new factories arriving at once may expose them more sharply, giving investors a live comparison against Hanoi or Jakarta.
Not every Chinese investor sees it unfavourably.
Lee Wai Choong, managing director of a Chinese-owned furniture manufacturer at Mirsharai Economic Zone, points to Bangladesh’s labour-cost advantage as reason enough to invest and grow, with room to move up the value chain if the country builds deliberately on that base.
Al Mamun Mridha, former BCCCI secretary general, is more critical: “Countries like Thailand and Vietnam have aggressively promoted their economic zones to Chinese investors. Bangladesh has not done the same. If Chinese investors come independently and ask for h elp, we support them — but this doesn’t attract new investment.”
That makes the China opportunity, in an unglamorous sense, a test of Bangladesh’s own reform agenda as much as Chinese intent.
The strategy Bangladesh never fully adopted
Why has the gap between Chinese interest and actual production persisted so long? One answer: Bangladesh has not always targeted the investment it needs.
M Masrur Reaz, chairman of Policy Exchange Bangladesh, points to a basic contradiction — Bangladesh has had duty-free access to China for thousands of products since 2020, yet exports have not risen as expected.
The problem, he says, is not market access but scale, productivity and competitiveness: Bangladesh needs to produce goods Chinese consumers and businesses actually want.
“Duty-free market access alone is not enough to increase exports,” Reaz told Daily Sun, adding, “The country also needs to develop the capacity to produce products that are in demand and competitive in that market.”
That is where Chinese investment could help — if Bangladesh deliberately targets sectors where Chinese companies bring capital, technology and supply-chain connections while producing for export, an opportunity growing as Chinese manufacturers seek bases outside China amid shifting supply chains and trade barriers.
“What’s needed now is to specifically identify the sectors in Bangladesh that have export potential in international markets and where Chinese investors may have an interest,” Reaz said.
The objective, then, should not be simply more Chinese investment — it should be the right investment, expanding Bangladesh’s productive and export capacity.
Building the institutional response
The government has begun responding institutionally, with both a name and a number behind it.
“Chinese investment has become one of the largest sources of foreign investment in Bangladesh over the past five years,” BIDA Executive Chairman Ashik Chowdhury has said, and the figures agree: China ranked second-largest source of private FDI in Bangladesh between 2019 and 2024, after Saudi Arabia, with roughly $4.38 billion from mainland China and a further $173 million from Hong Kong.
More recent Bangladesh Bank data sharpens the picture.
China was Bangladesh’s second-largest source of net FDI in 2025 alone, over 18% of total inflows — a six-year high — with cumulative investment approaching $2 billion.
The trajectory is steep: China wasn’t even among the top ten investors in 2016, ranked 16th with a 1.6% stock share. By 2025 it had climbed to third, holding nearly 10%, as its FDI stock surged more than 700% — from $241 million to nearly $2 billion.
BIDA now counts roughly 510 Chinese companies operating across manufacturing, power, textiles, construction and trading.
Part of the explanation, says Mutual Trust Bank MD Syed Mahbubur Rahman, is straightforwardly commercial: Bangladeshi businesses that once relied on European machinery increasingly source from China, where comparable equipment costs considerably less and quality is improving.
Chinese financing has also proved attractive for its accessibility — unlike IMF-style lending, it typically comes with fewer policy conditions, appealing to a government wanting quick access to capital for large projects.
BIDA plans to open its first overseas office in China, alongside the China Relationship Desk and Chinese-language “China Investment Gateway” already launched.
The office will be based in Guangzhou, says BIDA Executive Member Nahian Rahman Rochi, who says the authority has also built a dedicated relationship-management mechanism for Chinese investors, moving beyond case-by-case handling.
“This will allow us to respond faster to investor concerns and improve Bangladesh’s visibility in China,” Ashik Chowdhury said.
Prime Minister Tarique Rahman, addressing Chinese business leaders at BIDA’s Beijing seminar in June, put it similarly: “Our objective is simple. Chinese investors should not have to wait until they arrive in Bangladesh to receive support. We want to be closer to you, speak to you more regularly and help you move faster from interest to decision.” These measures should help. But investor facilitation cannot become investor accommodation at any cost, and some in Bangladesh’s business community are already saying so, pointing to law and order, banking-sector weaknesses, and frequent VAT and customs changes as the deterrents that actually matter.
Al Mamun Mridha has noted the China office idea had been under discussion for some time before finally moving forward — a reminder that response and delivery are not the same thing.
Mamun frames China’s engagement as unfolding in stages: an early machinery supplier offering favourable credit, then EPZ operations, then textile machinery, garments, backward-linkage industries, power and infrastructure financing — and now, manufacturing itself.
That progression is, in effect, a compressed version of the “second phase” traced through Anwara and the $9.21 billion pledge: each stage deepened the relationship, but none guaranteed the next.
The irony inside the imbalance
There is a structural irony here.
China is Bangladesh’s largest trading partner, but the relationship remains heavily tilted toward Chinese exports into Bangladesh — machinery, raw materials, electronics, chemicals, fabric.
Much of that, though, feeds Bangladesh’s own factories and export industries, so the imbalance so often cited as evidence of an unequal relationship also contains the outline of a different one.
If Chinese companies increasingly manufacture inside Bangladesh, source inputs locally, and use the country as an export base, some current imports could eventually be produced at home instead.
More significantly, Chinese capital, market knowledge and supply-chain access could help Bangladesh sell more into third-country markets altogether — the actual prize, as opposed to import substitution alone.
From investor to creditor
There is another side to this relationship: China is becoming an increasingly important creditor, not just an investor.
Bangladesh owed Chinese lenders $7.83 billion at the end of FY25, per Bangladesh Bank data; $3.37 billion of that was owed by private-sector companies, making China the largest private-sector creditor with a 34.2% share of total private-sector external debt, up sharply from $422 million in 2018.
The distinction matters: investment brings capital, technology and shared risk, while loans create repayment obligations regardless of a project’s performance.
Masrur Reaz says Bangladesh needs to assess Chinese-funded projects for their economic returns, not just their financing value.
The question is not whether Chinese lending is inherently problematic — it is whether borrowed money is channelled into projects capable of generating enough value, exports, employment or productivity gains to justify the liabilities they create.
That makes the shift from investment to production matter in another sense: projects must ultimately pay for themselves.
What the second phase will actually measure
The signs, taken together, are genuinely encouraging: Chinese companies dominating new EPZ commitments, strong participation in BIDA’s pipeline, Anwara finally under construction, a second China-linked zone taking shape around Mongla, and active courtship of Chinese manufacturers across electronics, batteries, medical devices and advanced textiles.
But the biggest number here — $9.21 billion — remains a promise, not an outcome.
The real story will be written somewhere less visible than a joint communiqué: in factories that open or don’t, in export figures that move or stay flat, in Bangladeshi engineers who genuinely acquire new skills rather than watch Chinese technicians work around them, and in how much of the money announced in Beijing this June survives the journey to production.
It will also be written in whether young men like Navidul Islam end up running a section of a factory floor in five years, or still watching it run from the gate.
Bangladesh has already lived through the first phase of its China partnership, measured in concrete. The second phase, if it arrives, will be measured in something harder to photograph and harder to fake.
The question is no longer how much China is willing to invest in Bangladesh. It is what kind of economy Bangladesh intends to build with that investment — and whether, eighteen months from now, the answer is visible in more than just the skyline over Anwara.
