


 For all latest news, follow the Daily Sun's Google News channel.


‘It's awful’: How tariffs, soaring fuel costs and higher interest rates are squeezing American companies
CNBC
Published: 20 Sep 2026, 11:38 PM
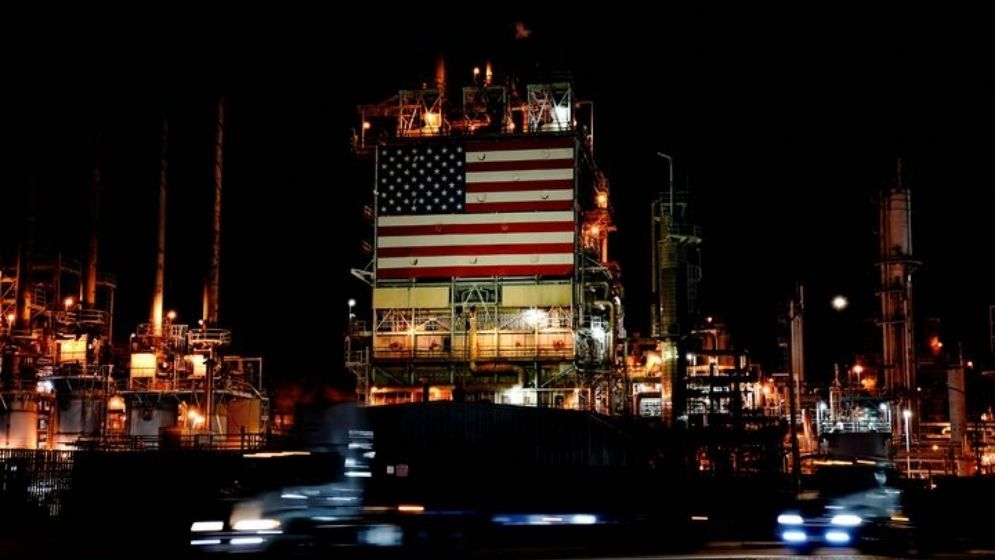
Semi trucks drive past a giant US flag displayed at Marathon Petroleum's Los Angeles Refinery in Carson, California, US. File Photo: Reuters
Fewer, pricier flights. Freight surcharges. Manufacturers hoarding inventory. Even bankruptcy.
For American
companies large and small, the combination of tariffs imposed under President
Donald Trump's trade policies, surging fuel prices from the Iran war and, now,
rising interest rates is forcing executives to make tough choices.
Allen Eden has
been holding onto extra inventory for his 25-person business, the Original Saw
Co. in Britt, Iowa, which makes industrial power saws for wood and metalwork,
as he grapples with spiking prices for aluminum, steel and essential parts.
One example: A
"little bracket" used for his saw motors more than doubled in price
this summer, surging to $87 from $42, he said.
"It's
awful," Eden, 56, told CNBC. "[I'm] just trying to keep more of the
stuff around because I don't know if we can get it down the road."
It's a
three-way squeeze for businesses across manufacturing, transportation and
retail: Tariffs are making raw materials and goods more expensive. Higher fuel
prices are pushing up the cost of making and moving them. And rising rates are
making it more expensive to finance the inventory and equipment businesses need
to keep running.
While few
sectors are completely insulated from these pressures, middle-market
manufacturers are caught in a particularly tight vise. Rising steel and fuel
costs are forcing them to pass at least some of those expenses on through
higher prices, helping feed the stubborn inflation of the past few years.
But to wrangle
inflation, the Federal Reserve raised interest rates for the first time in
three years and signaled another hike is possible this year. That makes it more
expensive for businesses to finance inventory and borrow for growth at the same
time that higher input costs and record prices for diesel, which is used for
trucking, squeeze margins.
Price
increases for Eden's saws, sold both to megaretailers like Home Depot and
directly to small- and medium-sized manufacturers, look inevitable, the
business owner said.
The pain isn't
being evenly distributed. Smaller companies typically rely on shorter-term
lending, meaning Fed hikes pass more directly into their costs, JPMorgan Chase
global strategy head Dubravko Lakos-Bujas said in a Sept. 14 note.
But regardless
of size, capital-intensive sectors like manufacturing and equipment suppliers,
logistics firms including trucking fleets, and commercial real estate also
suffer more in a rising-rate environment, according to Lakos-Bujas.
"The
combination of higher rates and higher fuel prices means that sectors with
heavy exposure to both are first in the line of fire," said Gregory Daco,
chief economist at EY-Parthenon, the global consulting arm of Ernst &
Young.
"Any type
of manufacturing is going to be disproportionately exposed to higher fuel
prices," he said.
Rising fuel
and commodity costs have strained both material makers and the retailers they
serve.
Mark Costa,
CEO of industrial giant Eastman Chemical, said in May that the one-two punch of
interest rates and inflation was forcing his industry into a corner. Eastman
makes the plastics, additives, and other materials used in products as diverse
as medical devices, animal feed, and car windshields.
"Everyone
had their back against the wall and had no room to absorb these
increases," Costa said. "Everyone is very quickly raising prices
faster than I've ever seen in 20 years."
On the retail
side, unexpected pressure from energy and raw materials costs will "fully
offset" the benefit of $730 million in tariff refunds, Home Depot CFO Richard
McPhail said last month.
"There's
just so much uncertainty right now. … You think inflation, interest rates, fuel
prices," McPhail said last week at a conference.
Supply chain
holes
Among those
hardest hit are manufacturers in the domestic automobile supply chain.
Lucerne
International, a privately held auto parts maker based in suburban Detroit,
stopped manufacturing operations in the U.S. and canceled plans last year for a
$50 million aluminum forging plant in Michigan.
"The
onset of the Trump tariffs 2.0 has just really torn holes in our global supply
chains and increased costs significantly," Lucerne CEO Mary Buchzeiger
said, citing higher costs for raw materials, including aluminum, as well as
finished parts.
Buchzeiger,
whose firm still manufactures overseas, said she has shifted U.S. operations to
warehousing, distribution, and tariff-mitigation solutions for other companies,
which offer "much better margins."
"There's
no doubt that there's margin pressure for suppliers," Paul McCarthy, CEO
of vehicle supplier trade association MEMA, said. "Some of it, we try to
absorb … and then some of it does have to be passed on."
Growth, as
measured by earnings before interest and taxes for the top 100 auto suppliers,
fell last year to 4.2%, down from more than 6% in 2021, according to consulting
firm Berylls by AlixPartners. Among the top 10 automakers, that figure is 5.2%,
down from nearly 8% in 2022.
Not all auto
companies have managed the additional costs. Spanish auto parts maker Grupo
Antolin, which supplies components to automakers including Ford, GM, Volkswagen
and Stellantis, filed for Chapter 15 bankruptcy protection in the U.S. in July.
The company cited tariffs, higher raw-material and energy costs, and
supply-chain disruptions as reasons for its restructuring.
Divide in
corporate America
Better off are
the giants of the corporate world, like the tech and finance companies that
fill the S&P 500. These firms typically have more cash reserves and take
out long-term debt, insulating them somewhat from the sting of higher rates.
Most larger
companies can thrive until borrowing costs rise much further. The pain would
hit when the yield on the 10-year Treasury bond reaches 6%, up from around 5%
now, according to JPMorgan's Lakos-Bujas, who cited 80 years of data.
Borrowing
costs are expected to stay higher for longer. Persistent inflation, which
forced Warsh to raise the benchmark Fed rate against Trump's wishes, along with
heavy borrowing from the U.S. government, is keeping upward pressure on rates.
Across corporate
America, companies are grappling with these shocks in different ways. The
divide comes down to one question: Who has pricing power?
Some
industries have learned they can readily pass higher costs on to consumers,
while others are caught in a catch-22: If they raise prices too much, they risk
destroying demand.
Federal
Reserve Chair Kevin Warsh speaks during a news conference at Federal Reserve
headquarters in Washington, Sept. 16, 2026. Warsh discussed the central bank's
decision to raise interest rates for the first time since 2023 at a press
conference following its latest policy meeting.
Federal
Reserve Chair Kevin Warsh speaks during a news conference at Federal Reserve
headquarters in Washington, Sept. 16, 2026. Warsh discussed the central bank's
decision to raise interest rates for the first time since 2023 at a press
conference following its latest policy meeting.
Airline
executives last week boasted of higher fares as customers keep booking trips,
especially abroad, allowing them to pass increased fuel costs on to travelers.
Airlines scaled back growth plans, cutting less profitable flights even after
the collapse of Spirit Airlines this year.
Fewer flights
can mean pricier airline tickets, and fares were up more than 23% in August
from last year, according to the latest inflation read. Yet even strong demand
has its limits.
"The
consumer has been incredibly, incredibly resilient," United Chief
Financial Officer Mike Leskinen said Wednesday during a Morgan Stanley conference
in Laguna Beach, California.
"But
there's some marginal routes that don't make sense in a higher fuel
environment. So we cut them," Leskinen said. "You should see us continue
to ... behave that way."
Much of
corporate America remains resilient despite higher fuel and financing costs.
Profit margins for major companies hover near historic highs, propelled by
strong productivity gains, labor costs that have stayed in check and surging
artificial intelligence investment that is driving growth.
But a risk of
Warsh's efforts is that higher rates don't directly address the root causes of
inflation: the Iran war, the Trump administration's tariffs, and the AI boom,
which has driven up the prices for everything required to build and run data
centers, from electricity to memory chips, copper, and land.
Raising rates
to tap the brakes on the US economy could slow it down too much, or send stocks
into a tailspin, said EY-Parthenon's Daco.
"The
economy is resilient, but it's exposed to growing pockets of risk," he
said. "A shock could materialise faster than we all think."