


 For all latest news, follow the Daily Sun's Google News channel.


IMF says world avoids worst of Mideast energy shock, but risks remain high
Reuters, Washington
Published: 11 Sep 2026, 04:13 AM
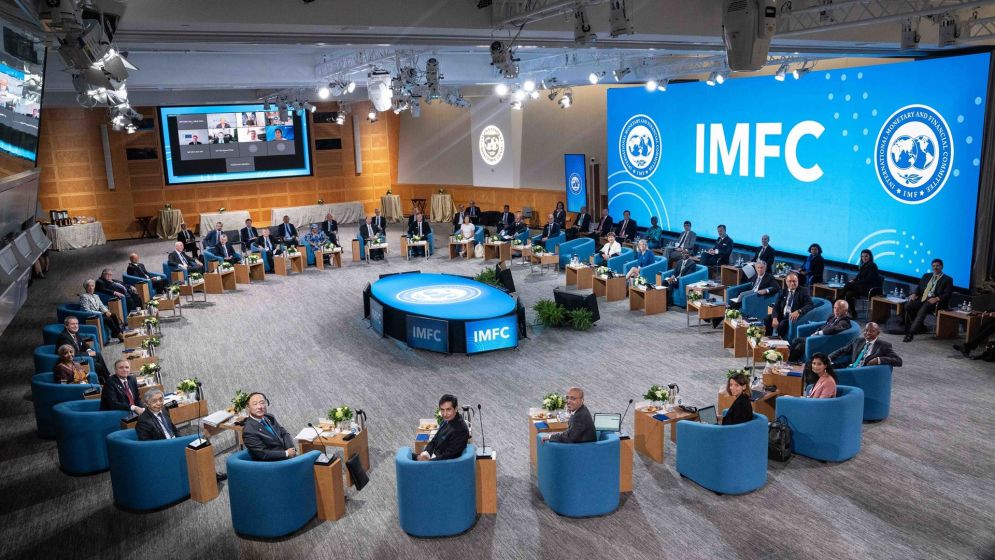
The IMF said on Thursday the global economy had weathered
the energy shock caused by the war in the Middle East better than feared and
global economic output was still expected to expand by about 3% in 2026, but it
cautioned that risks remained high.
Julie Kozack, spokesperson for the International Monetary
Fund, said oil and gas prices remained elevated and the energy shock from the
war was not over. Global debt pressures were also mounting and the disinflation
process over the 2022 cost-of-living crisis had stalled.
Global inflationary expectations have risen but remain
well-anchored over the longer run, Kozack told a regular IMF briefing.
"So far, despite six months
of war in the Middle East, the global economy has been resilient," Kozack
said, adding that the use of oil and gas reserves had allowed some countries to
cope with energy shocks caused by the war, while others had shifted to new
energy sources or acted to curb demand.
"We remain on track for world growth of around 3% but
uncertainty, as we've been saying for quite some time, continues to remain
high," she said.
The IMF in July forecast 2026 global growth at a sluggish
3.0%, compared with an average of 3.5% seen in 2024 and 2025, and its April
forecast of 3.1%. At the time, it said that forecast assumed the war would wind
down in mid-July, but Iran and the United States have both escalated their
attacks and the war has widened with increased military activity in Yemen.
The global lender will release an updated forecast during
the annual meetings of the IMF and the World Bank in Bangkok from 12 to 18 October.
Pulled in opposite directions
Kozack said the global economy was being pulled in opposite
directions by the negative energy supply shock that was driving prices of
energy, fertilizers, food and other commodities sharply higher, while the
AI-led technology cycle was providing a positive demand shock.
Risks remain high, with many countries needing to restock
their oil and gas reserves, and energy demands set to rise as winter approaches
in the Northern Hemisphere, she said.
Pressures are also mounting on global public debt, which is
already at nearly 100% of gross
domestic product — the highest level since World
War Two — and is set to rise further, Kozack said.
Many advanced economies have particularly high public-debt-to-GDP ratios.
Liquidity problems are also building in developing
countries, including in Africa, partly due to a reduction in bilateral
assistance, Kozack said.
The IMF is urging central bankers to stick to their price
stability mandates, while
encouraging fiscal policymakers to develop medium-term consolidation plans, she
said.
"We're not in a situation where fiscal consolidation
needs to take place overnight, but having a clear, laid-out plan and strategy
for how deficits and debt are going to come down is very important for fiscal
authorities," Kozack said.
The IMF was also urging
authorities to focus on lifting growth prospects through structural reforms and
removing "self-inflicted" barriers to growth, she said.
Kozack said the IMF would look closely at the impact of new
US sanctions against Iran, including secondary sanctions aimed at firms in
third countries that support Tehran. A fuller report was expected in the
upcoming global outlook, she said.