


 For all latest news, follow the Daily Sun's Google News channel.
Huafa’s $62b debt strain shakes China’s credit market
Bloomberg
Published: 03 Nov 2026, 08:20 PM
China’s credit market just suffered its worst selloff in two years as a major conglomerate’s plunge into distress tests the assumption that government ties can protect state-owned firms from financial peril.
In
just a few days, Zhuhai Huafa Group Co called that view into question. The
conglomerate, wholly-owned by local governments in the southern province of
Guangdong, missed payments on two trust products and asked to extend some bank
loans, people familiar with the matter said last Monday.
By
Friday, unease was mounting as investors came to terms with the implications in
a country where missed debt payments by state-owned firms had become rare. Over
the two days through Monday, money managers pushed the average yield they
demand to hold benchmark Chinese corporate bonds up 10.3 basis points, the
worst two-day stretch since October 2024. Those rates on three-year yuan notes
with the same local AAA ratings as Huafa were little changed Tuesday morning,
traders said.
The
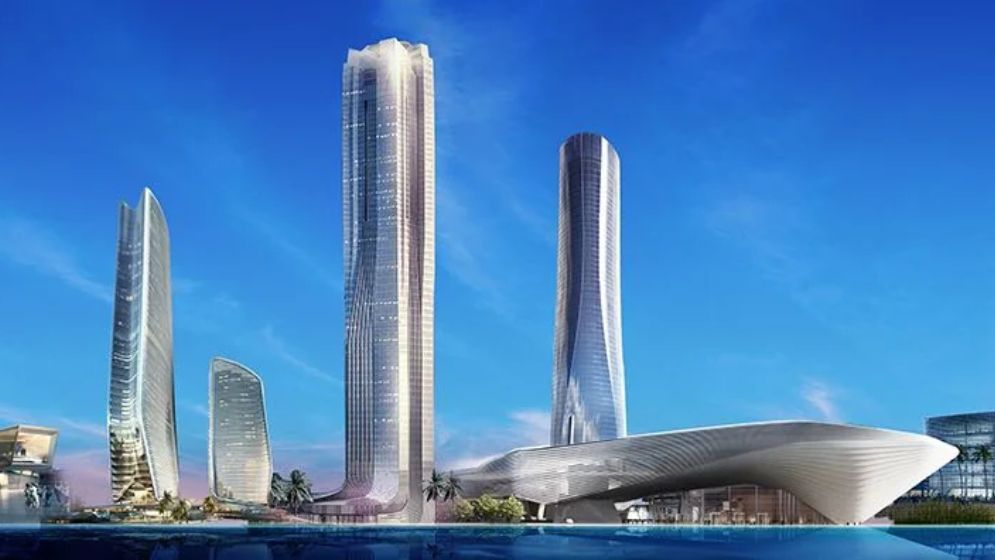
crisis at Huafa, which has helped build landmarks such as the 330m tall Zhuhai
Tower skyscraper, is spotlighting risks among Chinese state-owned firms reliant
on implicit government support as a years-long property downturn and slowing
economic growth hurt profitability. Its offshore bonds tumbled to distressed
levels as low as about 54% of face value last week, as concern mounted over its
RMB413 billion of interest-bearing liabilities.
“Local
government financing vehicles and some state-owned firms with weak standalone
credit profiles are just a ticking time bomb,” said Zerlina Zeng, head of Asia
credit strategy at Creditsights Singapore.
The
shock from Huafa even briefly spilled beyond the onshore credit market. Chinese
high-yield dollar notes suffered their worst week in about a year last week. In
the local sovereign debt market, 30-year government bond futures posted their
biggest daily drop since March on Friday, with traders citing Huafa as a drag
on sentiment across markets.
The
conglomerate’s stumble stands out, after accommodative monetary policy in
recent years and an unprecedented government push to contain debt risks tied to
local authorities helped avoid such outcomes. It also raises concerns given
Huafa’s home base of Guangdong, which has China’s biggest provincial economy.
“Almost
every major financial institution I know holds Huafa bonds, especially
state-owned institutions,” according to Li Huan, co-founder of asset manager
Forest Capital Hong Kong Ltd.
To
some investors, the situation recalls refinancing stress that swept through
China’s coal sector after a surprise default by a state-run miner roiled
markets in late 2020. The miner ultimately made full payment on its bonds
months later as local authorities moved to restore market confidence.
Huafa’s
offshore yuan-denominated securities due in 2027 have pared some of their
earlier losses, recovering to about 63% of face value. That comes after news
that it had repaid one of its trust products and that its property arm made
good on payments due Monday on a yuan note.
Still,
uncertainty persists over the company’s liabilities in the longer term and,
more broadly, over the extent to which China will support its debt-laden
state-owned firms.
If
Huafa continues to repay its public bonds and makes progress on asset
monetisation, the concerns could prove to be a temporary liquidity crunch
contained by local authorities, according to a research note from China
Zheshang Bank Co. But bond extensions or even potential restructurings could
trigger a broader reassessment of the state-owned sector, the note said.
Huafa
is about 93.5% owned by Zhuhai’s State-Owned Assets Supervision and
Administration Commission, with Guangdong’s provincial finance department
owning the remainder. The company had about RMB765 billion in total assets as
of March.
The
conglomerate, which derived about half of its revenue from property development
and urban operations last year while also running businesses spanning financial
services and technology, had blamed the property downturn as the main reason
for its profitability swings.
A
few days ago, its real estate arm reported a RMB6.44 billion net loss in the first
nine months of this year.
To
stay ahead of Singapore and the region’s corporate and economic trends, click
here for Latest Section
Huafa
was placed last week on rating watch negative by Fitch Ratings, which scores it
at BBB, toward the lower end of investment grade. The step signals the increased
possibility of a downgrade.
Fitch
cited the company’s “weakening debt-service coverage, approaching near-term
debt maturities and widening issuer bond spreads amidst unconfirmed market
rumours of potential debt-maturity extensions”.