


 For all latest news, follow the Daily Sun's Google News channel.


Rising NPLs disrupt loan recycling, squeeze banks’ lending capacity: Mahbub Ullah
Daily Sun Report, Dhaka
Published: 19 Sep 2026, 09:46 PM
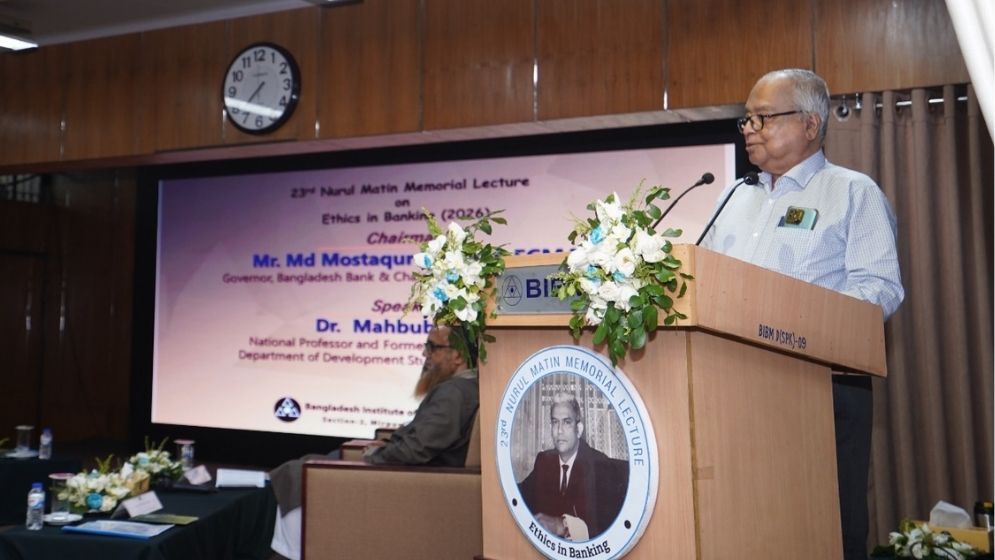
Photo: Courtesy
The rising trend of non-performing loans (NPLs), which now account for more than 32% of total loans in Bangladesh’s banking sector, is disrupting the normal cycle of loan recovery and reinvestment, National Professor Dr Mahbub Ullah has said.
The
situation is putting pressure on banks’ liquidity, profitability and capital
adequacy while restricting fresh lending to businesses and industries, he said.
Mahbub
Ullah, former professor and chairman of the Department of Development Studies
at the University of Dhaka, made the remarks while delivering the 23rd Nurul
Matin Memorial Lecture on “Ethics in Banking”, organised by the Bangladesh
Institute of Bank Management (BIBM) in Dhaka on Saturday.
Bangladesh
Bank Governor and Chairman of the BIBM Governing Board Md Mostaqur Rahman presided
over the programme. BIBM Director General Dr Md Ezazul Islam delivered the
welcome address, while Professor and Director (Research, Development and
Consultancy) Md Shihab Uddin Khan delivered the vote of thanks.
In
his lecture, Mahbub Ullah said the core driving force of banking is the
continuous recycling of loan funds within the economy.
Banks
collect deposits from customers and disburse the funds as loans. When borrowers
repay instalments and interest, the recovered funds are again lent to new
borrowers, creating a continuous cycle of financing economic activities.
But
the growing volume of defaulted loans is disrupting this cycle, he said.
“A
significant portion of depositors’ funds, once disbursed as loans, is not
returning to banks on time,” he noted, adding that this is putting pressure on
banks’ liquidity and their capacity to extend new credit.
At
the same time, banks are becoming increasingly cautious about approving fresh
loans because of the heightened credit risks, he said.
Mahbub
Ullah said prolonged losses and rising defaulted loans are also making it
difficult for some banks to maintain the capital reserves required under
Basel-II standards.
This
is further limiting their capacity to extend fresh credit, while even
financially stronger banks are adopting a cautious approach to lending to
minimise risks.
As
a result, eligible entrepreneurs and industrial enterprises are facing
difficulties in obtaining working capital and investment financing, which could
affect production, employment and overall economic activity, he said.
He
warned that risks in the banking sector could rise further unless effective and
sustainable measures are taken to contain defaulted loans.
He
stressed the need for good governance, accountability, ethics and sound risk
management in loan approval and recovery.
Restoring
confidence in the banking sector, recovering defaulted loans, strengthening
banks’ capital base and ensuring a normal flow of credit to eligible businesses
require coordinated and effective measures, he added.
Trust
is the core strength of banks: Governor
Bangladesh
Bank Governor Md Mostaqur Rahman placed emphasis on ethics, good governance,
accountability and professionalism in the banking sector.
He
said the strength of a bank does not depend only on its capital, technology or
liquidity, but also on the trust of depositors, borrowers, investors and the
broader economy.
According
to him, trust is the most important foundation of the banking system, and
bankers must maintain the highest professional and ethical standards to
preserve it.
Ethical
decisions crucial in lending
BIBM
Director General Dr Md Ezazul Islam said banking is different from many other
businesses because banks manage public deposits and channel those funds into productive
economic activities.
Therefore,
decisions made by bankers affect not only individual banks or customers but
also various sectors of the economy, he said.
He
said a competent banker should have expertise in accounting, economics, credit
analysis and other technical areas, but professional competence alone is not
enough.
Honesty,
responsibility, ethics and accountability are particularly important in areas
such as loan approval, rescheduling, asset valuation, customer selection and
risk management, he added.
Ezazul
Islam also highlighted the role of bank boards and top management in
establishing an ethical culture within financial institutions.
“If
integrity, transparency and accountability begin at the top level of an
institution, they will gradually be reflected throughout the organisation,” he
said.