


 For all latest news, follow the Daily Sun's Google News channel.


Insurance firm licence renewals stalled over revised fee confusion
IDRA asks insurers to pay higher rates introduced after applications were filed; sector seeks swift resolution to avoid disruption
The renewal of insurance company licences has been delayed following complications arising from revised registration renewal fee regulations.
Insurance companies had applied for licence renewal in November by paying the prescribed fees in line with existing rules.
However, on 4 February, the government published a gazette notification introducing a revised fee structure.
Two months after companies submitted their payments, the Insurance Development and Regulatory Authority (IDRA) instructed them to pay the increased fees under the new regulation.
Under the law, insurers must apply for licence renewal by November each year by submitting the
required fees to IDRA, which typically completes verification and renewal procedures by December.
While this year’s process was initially proceeding as usual, the revised regulations altered the fee structure midway through the cycle.
As a result, IDRA has asked companies to pay the remaining amount in accordance with the updated rates before their 2026 renewal certificates can be issued.
Speaking to Daily Sun, IDRA spokesperson Saifunnahar Sumi said the absence of a renewal certificate does not automatically render a company’s operations illegal.
A licence may be cancelled only if a company fails to apply within the stipulated timeframe, she said.
Once an application is submitted, the regulator requires time to verify documents and process the renewal.
There is no provision stating that a company cannot operate or that its licence stands cancelled during the verification period, she added.
Sumi said that following the publication of the gazette on revised renewal fees, all companies have been directed to pay the newly determined rates.
“Once the revised fees are paid, the renewal process will be
completed. There is no reason for confusion,” she said.
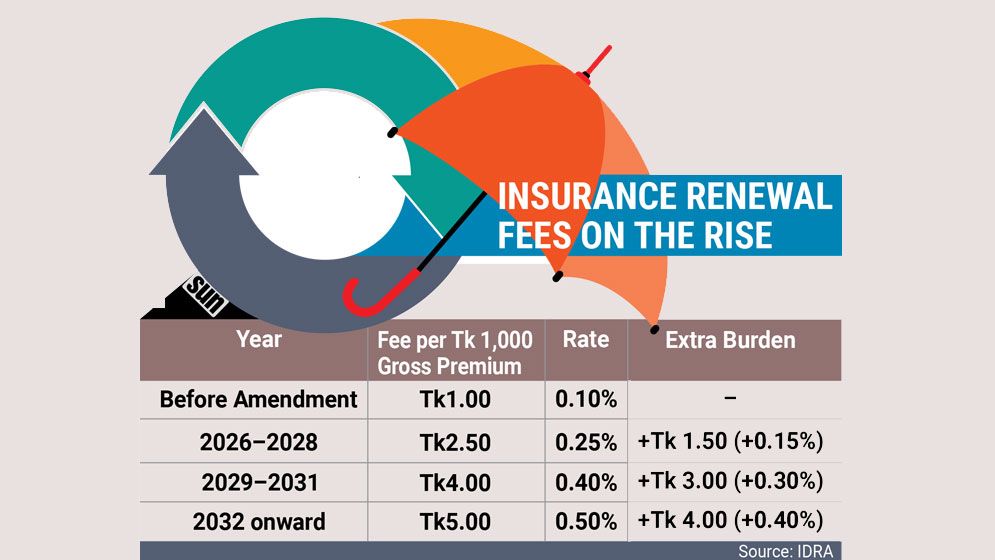
According to the amended regulation, insurance companies will have to pay Tk2.50 per Tk1,000 of gross premium income for the years 2026-28, up from the previous Tk1 per thousand.
The rate will rise to Tk4 per thousand for the following three years and to Tk5 per thousand from 2032 onward, effectively increasing the fee from 0.1% to 0.5% in phases.
In a letter sent on 1 March, IDRA said the remaining fees under the revised structure must be paid to obtain the 2026 licence renewal certificate.
SM Nuruzzaman, chief executive officer of Zenith Islami Life Insurance PLC, said the company had applied for renewal within the stipulated timeframe.
“We have now received a letter from IDRA asking us to pay the revised fees, and we are taking steps to comply,” he said.
He added that since companies are not permitted to issue new policies or settle claims without renewal under the law, the regulator should resolve the matter promptly to avoid disruption to normal operations.
Industry sources said insurers complied with the rules in place at the time of application and that the subsequent
revision has created uncertainty within the sector.
According to the latest regulatory data, Bangladesh has 82 licensed insurance companies operating under IDRA’s supervision, including 36 life insurers and 46 non-life (general) insurance companies.